Meta Description: What is retirement planning and why should you start early? Learn how to calculate your retirement corpus, leverage compounding, and secure your golden years.
Introduction: Why Your Future Self Depends on What You Do Today
When you are in your twenties or thirties, retirement feels like a lifetime away. Day-to-day priorities—such as paying rent, managing career goals, and buying daily conveniences—take up all our mental bandwidth. However, time moves faster than we realize, and the day will eventually come when you will want to step away from the daily grind and live life on your own terms.
Without a structured retirement plan, your golden years can quickly turn into a period of financial stress. The secret to a comfortable, secure retirement is not earning a massive fortune overnight; rather, it is about starting early, maintaining discipline, and letting compound interest do the heavy lifting. In this comprehensive guide, we will break down how to plan your retirement corpus, calculate your future expenses, and secure financial freedom.
What is Retirement Planning and Why Start Early?
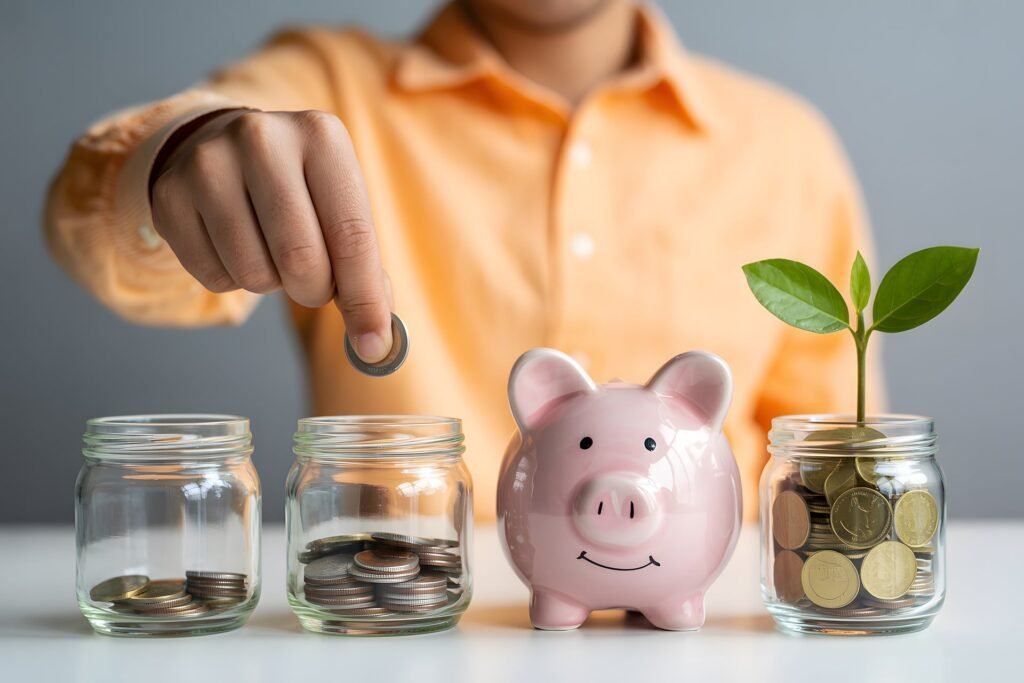
Retirement planning is the process of setting aside funds and investing capital today so that you can maintain your standard of living and support your lifestyle after you stop working.
The single greatest ally in retirement planning is time. Because of the magic of compound interest, a person who starts investing $200 a month at age 25 will often end up with significantly more wealth by age 60 than someone who starts investing $500 a month at age 40. Starting early means your money works harder and longer for you.
How to Calculate Your Required Retirement Corpus
To figure out how much money you need to save before retiring, you must factor in three critical variables: your current age, your target retirement age, and the impact of inflation on future living expenses.
1. Account for Inflation
Inflation eats away at purchasing power. A lifestyle that costs $1,000 per month today will cost significantly more 20 or 30 years from now. Assuming an average annual inflation rate of 6%, your living expenses will roughly double every 12 years.
2. The 4% Rule (Safe Withdrawal Rule)
A widely used thumb rule in financial planning is the 4% Rule. It suggests that once you retire, you can safely withdraw 4% of your total accumulated retirement corpus in the first year, and adjust that amount for inflation in subsequent years, without running out of money for at least 30 years.
- Formula: If your annual post-retirement expense is $40,000, multiply it by 25 to find your target corpus ($\$40,000 \times 25 = \mathbf{\$1,000,000}$).
(You can experiment with various investment timelines and expected returns using the iNDiAN Calc Investment & SIP Calculators to map out your exact target).
4 Pillars of a Bulletproof Retirement Strategy
- Maximize Long-Term Equity Exposure Early: During your working years, allocate a healthy portion of your portfolio to equity mutual funds via systematic investment plans (SIPs) to outpace inflation.
- Shift to Safer Assets Gradually: As you get closer to retirement age (e.g., 5 to 10 years away), systematically rebalance your portfolio by shifting gains from high-risk equities into stable fixed-income assets or debt funds to protect your capital.
- Clear All High-Interest Debt: Never enter retirement carrying home loans, auto loans, or credit card balances. Entering your golden years completely debt-free drastically reduces your monthly cash-flow requirements.
- Maintain Comprehensive Health Insurance: Medical costs tend to rise sharply during old age. Having a dedicated, standalone health insurance policy ensures that a sudden medical emergency doesn’t wipe out your entire retirement savings.
Frequently Asked Questions (FAQs)
Q1: What age is ideal to start planning for retirement?
Ans: The ideal age to start is as soon as you get your first job or stable income. Even if you start with a tiny amount, getting an early start maximizes the compounding effect.
Q2: Will social security or government pensions be enough?
Ans: In most modern economic environments, government pensions or basic social security payouts are rarely enough to maintain your pre-retirement lifestyle or handle rising medical inflation. Building a private investment corpus is essential.
Conclusion
Retirement planning is the ultimate act of self-care for your future self. By understanding inflation, calculating your target corpus, starting your investments early, and staying consistent, you can trade financial anxiety for complete peace of mind. Build your roadmap today so your golden years truly shine.
Disclaimer: This article is for informational and educational purposes only. Financial markets carry risks; consult a certified financial planner or wealth manager to build a customized retirement portfolio.