Understanding your actual in-hand salary can often feel confusing, especially with recent changes to financial rules and tax slabs. When you receive a job offer or annual hike letter stating a lucrative Cost to Company (CTC), the amount deposited into your bank account at the end of the month is usually lower.
In this comprehensive guide, we will break down the entire process of take home salary calculation with new tax regime 2026. You will learn how CTC differs from gross salary, how statutory deductions like Provident Fund (PF) work, and how the updated tax regime impacts your monthly payout.
What is CTC, Gross Salary, and Net Take-Home Salary?
Before diving into the numbers, it is essential to understand the three primary layers of your salary structure:
- Cost to Company (CTC): This represents the total annual expenditure an employer incurs on an employee. It includes direct components like basic pay and allowances, along with indirect perks such as health insurance, gratuity, and the employer’s share of PF.
- Gross Salary: This is the total pay earned before any direct taxes or statutory deductions. It equals CTC minus indirect employer expenses (like employer PF contribution and gratuity).
- Net Take-Home Salary: This is the exact amount credited to your bank account each month. It is calculated as Gross Salary minus employee statutory deductions (Employee PF, Professional Tax/TDS).
$$\text{Net Take-Home Salary} = \text{Gross Salary} – (\text{Employee PF} + \text{TDS / Income Tax} + \text{Other Deductions})$$
New Tax Regime Slabs for 2026
Under the updated tax structure, taxpayers benefit from lower progressive tax rates and a simplified tax assessment model. Salaried individuals automatically get an increased Standard Deduction of ₹75,000.
Here is the current income tax slab structure under the New Tax Regime:
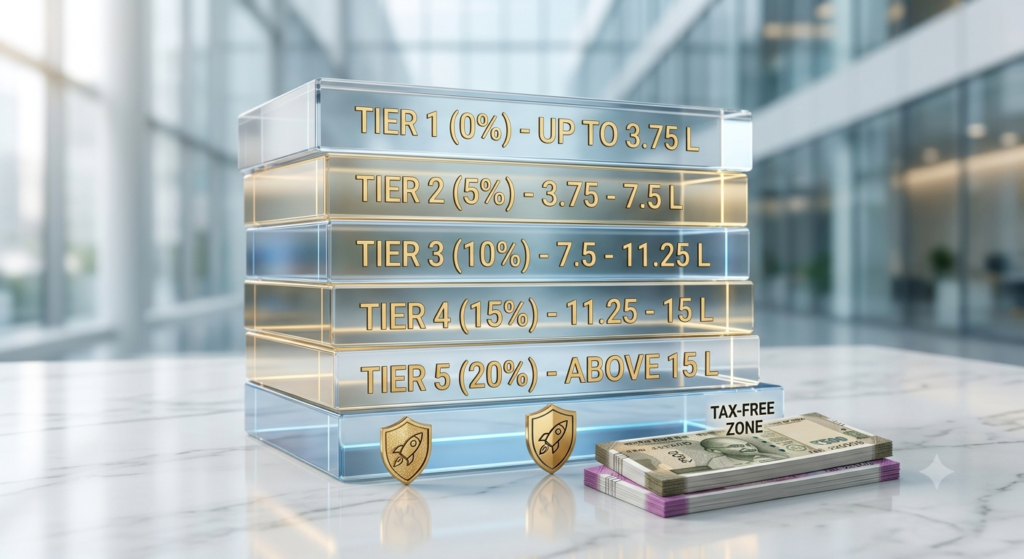
| Taxable Income Range | Applicable Tax Rate |
| Up to ₹4,00,000 | NIL |
| ₹4,00,001 to ₹8,00,000 | 5% |
| ₹8,00,001 to ₹12,00,000 | 10% |
| ₹12,00,001 to ₹16,00,000 | 15% |
| ₹16,00,001 to ₹20,00,000 | 20% |
| ₹20,00,001 to ₹24,00,000 | 25% |
| Above ₹24,00,000 | 30% |
Key Advantage: Resident individuals with a total taxable income up to ₹12,00,000 can claim full tax rebate under Section 87A (up to ₹60,000 rebate). This effectively means salaried professionals earning up to ₹12.75 Lakhs annually (after accounting for the ₹75,000 standard deduction) pay ZERO income tax.
Step-by-Step Take Home Salary Calculation with New Tax Regime 2026
Let us walk through a practical example of how to calculate your net salary from annual CTC.
Example Scenario:
- Annual CTC: ₹12,00,000 (12 Lakhs)
- Basic Salary (50% of CTC): ₹6,00,000 per year (₹50,000/month)
- House Rent Allowance (HRA) & Special Allowances: ₹5,00,000 per year
- Employer PF Contribution (12% of Basic): ₹72,000 per year
Step 1: Calculate Gross Salary
Subtract employer-only contributions (like Employer PF and Gratuity) from your CTC:
$$\text{Gross Salary} = \text{CTC } (₹12,00,000) – \text{Employer PF } (₹72,000) = ₹11,28,000 \text{ per year}$$
Step 2: Calculate Taxable Income
Apply the standard deduction of ₹75,000 to determine your final taxable base:
$$\text{Taxable Income} = \text{Gross Salary } (₹11,28,000) – \text{Standard Deduction } (₹75,000) = ₹10,53,000$$
Step 3: Compute Income Tax Payable
Since the taxable income (₹10,53,000) is below ₹12,00,000, the individual qualifies for full tax rebate under Section 87A:
- Up to ₹4,00,000: ₹0
- ₹4,00,001 to ₹8,00,000 (5%): ₹20,00,000 $\times$ 5% = ₹20,000
- ₹8,00,001 to ₹10,53,000 (10%): ₹2,53,000 $\times$ 10% = ₹25,300
- Total Tax Before Rebate: ₹45,300
- Less Section 87A Rebate: -₹45,300
- Net Income Tax (TDS): ₹0
Step 4: Deduct Employee Statutory Contributions
Deduct Employee PF (12% of Basic Pay) from the Gross Salary:
$$\text{Annual Employee PF} = 12\% \text{ of } ₹6,00,000 = ₹72,000$$
Step 5: Final Net Salary Payout
$$\text{Annual Net Take-Home} = \text{Gross Pay } (₹11,28,000) – \text{Employee PF } (₹72,000) = ₹10,56,000$$
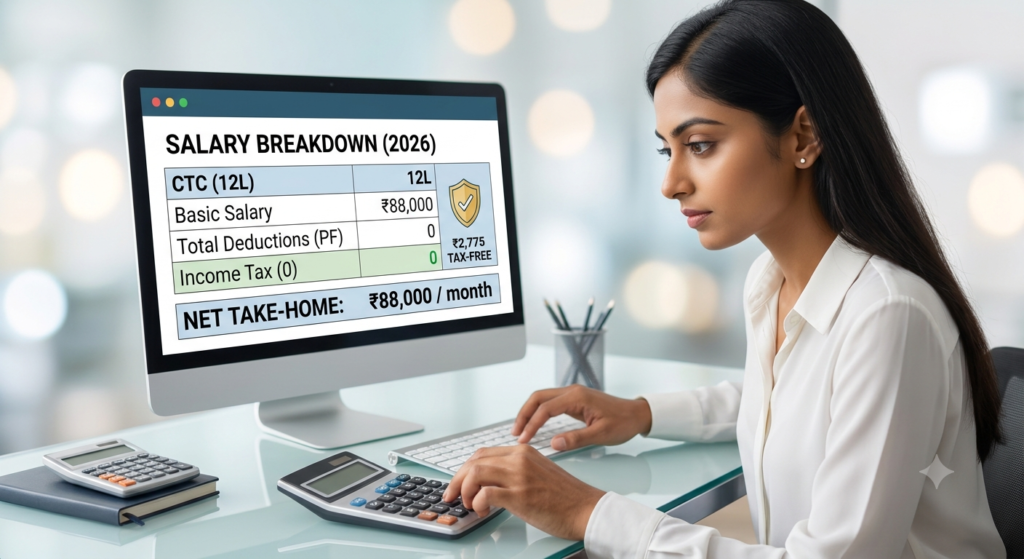
$$\text{Monthly Net Take-Home Salary} = \frac{₹10,56,000}{12} = \mathbf{₹88,000 \text{ per month}}$$
Essential Salary Calculation Checklist
To ensure your salary calculation stays completely accurate, keep these vital factors in mind:
- Basic Salary Percentage: Most organizations structure Basic Pay at 40% to 50% of total CTC.
- Statutory Provident Fund: PF is split equally between employee and employer (typically 12% of Basic Pay).
- Exemptions under New Regime: Remember that traditional exemptions under Section 80C, 80D, and HRA are not allowed under the New Tax Regime. However, the higher tax rebates and simplified structure offer substantial savings for most middle-income earners.
- Regional Differences: If you are calculating salaries for cross-border teams or foreign remote setups, always account for country-specific labor laws and tax thresholds.
Calculate Your Take-Home Pay instantly
Manual salary calculations can be time-consuming and prone to manual errors. Use our free digital calculators to evaluate your exact monthly earnings and plan your finances effortlessly:
- Calculate your exact take-home pay in seconds using our free Salary Calculator tool.
- Planning a loan or investment alongside your monthly salary? Check your monthly repayments with our clean and fast Home Loan EMI Calculator.
- Review official tax compliance policies directly at the Income Tax Department of India portal.
Frequently Asked Questions (FAQs)
1. Is standard deduction available in the new tax regime 2026?
Yes, salaried individuals can claim a flat Standard Deduction of ₹75,000 under the New Tax Regime.
2. Up to what income is salary tax-free in 2026?
Under the new tax regime rules, individuals earning a taxable salary up to ₹12 Lakhs enjoy zero income tax due to full tax rebates under Section 87A. When combined with the ₹75,000 standard deduction, a salary up to ₹12.75 Lakhs yields zero tax outgo.
3. What is the main difference between Old vs New Tax Regime?
The Old Tax Regime offers lower basic exemption limits but allows deductions under Section 80C, 80D, and HRA. The New Tax Regime features lower progressive tax slabs and a higher tax rebate threshold without needing complicated investment proofs.