Meta Description: Confused between SIP and Lump Sum investments? Learn the differences, pros and cons, and how to choose the right strategy to maximize your mutual fund returns.
Introduction: The Great Investment Dilemma
When you finally decide to enter the world of mutual funds and wealth creation, you are immediately met with a major strategic question: Should I invest all my money at once in a lump sum, or should I break it down into systematic monthly installments?
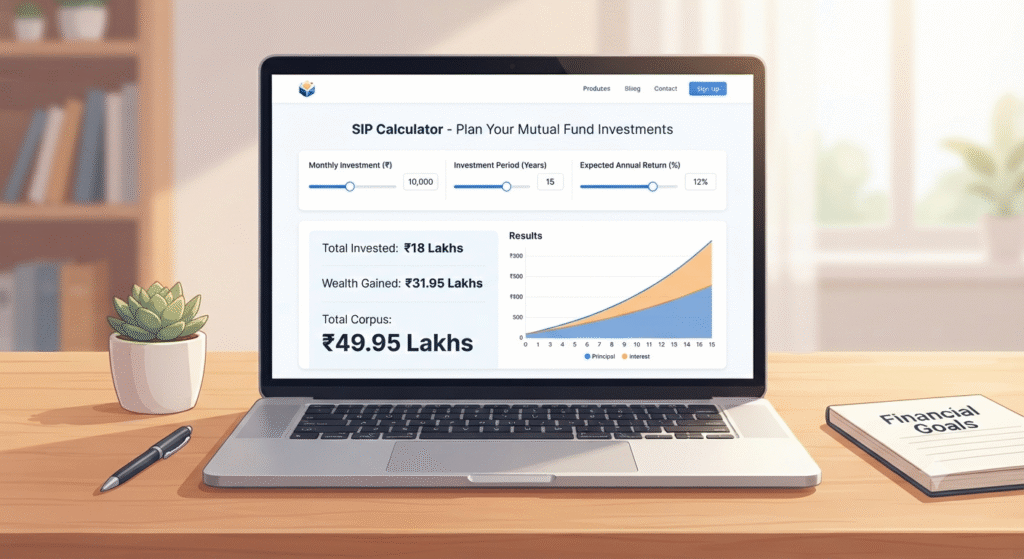
Choosing the right investment approach can significantly impact your portfolio’s performance, especially during volatile market phases. While both methods have distinct advantages, understanding how they work will help you align your capital with your financial goals. If you are exploring systematic investing, you can easily project your wealth growth using the iNDiAN Calc SIP Calculator. In this comprehensive guide, we will break down SIP versus Lump Sum investments to help you make an informed choice.
What is a SIP (Systematic Investment Plan)?
A SIP allows an investor to deposit a fixed amount of money into a mutual fund scheme at regular intervals—typically monthly or weekly.
Key Benefits of SIP:
- Rupee Cost Averaging: When markets are down, your fixed amount buys more units; when markets are high, it buys fewer. This naturally averages out your purchase cost over time.
- Disciplined Investing: It removes emotional decision-making from investing. By automating your contributions, you build a steady habit without needing to time the market.
- Pocket-Friendly: You can start with very small amounts, making it ideal for beginners, students, and young professionals. (For a deeper look at managing your monthly savings, check out our guide on Personal Budgeting and Wealth Building).
What is a Lump Sum Investment?
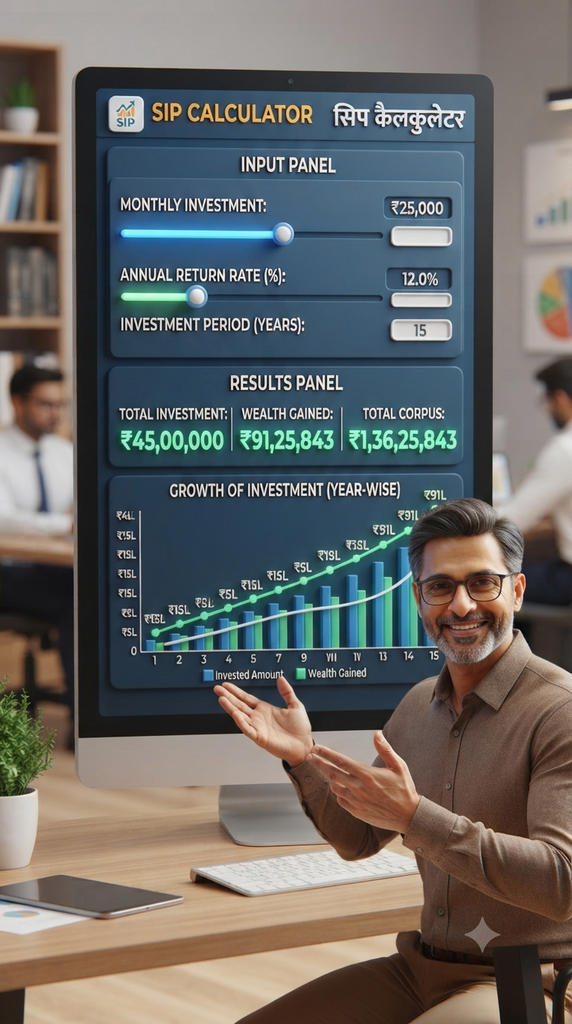
A Lump Sum investment involves deploying a large, one-time amount of capital into a mutual fund or financial asset all at once.
Key Benefits of Lump Sum:
- Power of Immediate Compounding: Your entire pool of capital starts working in the market right from day one. If markets trend upward over the long term, lump sum investments often outperform SIPs because more money is invested earlier.
- Ideal for Windfalls: Perfect for handling unexpected cash inflows such as business profits, performance bonuses, property sale proceeds, or inheritance money.
However, lump sum investing carries market-timing risk. If you invest a large amount right before a major market correction, your portfolio can suffer short-term drawdowns.
SIP vs. Lump Sum: Head-to-Head Comparison
| Feature | SIP (Systematic Investment Plan) | Lump Sum Investment |
| Capital Required | Low (Small monthly amounts) | High (Single large capital) |
| Market Timing Risk | Low (Averaged out over time) | High (Vulnerable to entry peaks) |
| Discipline Required | High (Requires regular monthly action) | Low (One-time transaction) |
| Best Suited For | Salaried individuals & regular earners | People with sudden cash windfalls |
To understand how your overall capital multiplies over time through compounding, you can explore the insights shared in our Compound Interest Wealth Guide.
Which Strategy Should You Choose?
The right choice depends entirely on your current cash flow and financial situation:
- Choose SIP if: You earn a regular monthly salary or income stream and want to build wealth gradually while keeping market volatility in check. (To ensure your monthly cash flow supports your investments without stress, review our tips on Managing Expenses and Emergency Funds).
- Choose Lump Sum if: You have a substantial lump sum sitting idle in a savings account and have a long-term investment horizon (5 to 10+ years) where short-term market dips won’t force you into premature withdrawals.
Frequently Asked Questions (FAQs)
Q1: Can I do both SIP and Lump Sum investments together?
Ans: Absolutely! Many seasoned investors use SIPs as their primary core wealth vehicle while occasionally deploying lump sum amounts into mutual funds whenever they receive extra cash or market corrections occur.
Q2: Is SIP completely risk-free?
Ans: No. While SIP reduces market timing risk through rupee cost averaging, mutual funds are still subject to market risks. Align your investments with your risk tolerance and financial timeline.
Conclusion
Both SIP and Lump Sum are powerful vehicles for wealth creation; neither is universally “better” than the other—they simply serve different financial scenarios. By matching your investment method to your income structure and keeping your eyes fixed on long-term horizons, you can build a robust financial future.
Disclaimer: This article is for informational and educational purposes only. Mutual fund investments are subject to market risks; consult a certified financial planner before deploying capital.