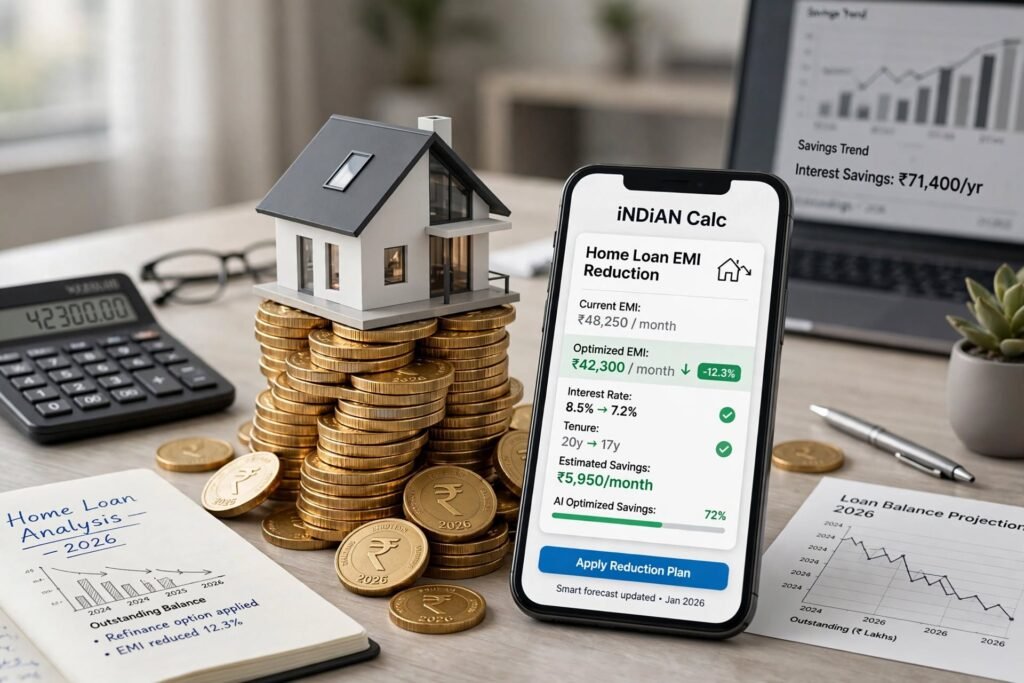
Taking out a home loan is a major milestone toward owning your dream home, but it is also one of the largest financial commitments you will make in your lifetime. With repayment tenures often stretching across 15 to 30 years, a significant portion of your monthly income gets tied down to Equated Monthly Installments (EMIs).
If not managed carefully, interest payments can end up exceeding the original principal amount borrowed. However, with strategic planning, disciplined prepayments, and periodic interest rate reviews, you can drastically reduce your financial burden and become debt-free years ahead of schedule.
Here is a practical, step-by-step guide on how to manage a home loan effectively in 2026.
1. Choose the Right Interest Rate Regime (Repo Rate Linked)
Most home loans in India are tied to floating interest rates linked to the Reserve Bank of India’s (RBI) External Benchmark Lending Rate (EBLR).
What You Should Do:
- Review your current interest rate: Ensure your loan is linked to the latest EBLR/Repo Rate benchmark rather than older regimes like MCLR or Base Rate. External benchmark rates pass on central bank rate cuts faster to borrowers.
- Negotiate with your lender: If your bank charges a higher spread than what they offer to new customers with similar credit scores, request a rate conversion. Paying a small processing fee to reduce your interest rate by even 0.25% to 0.50% can save you lakhs over a 20-year tenure.
2. Make Prepayments Early in the Loan Tenure
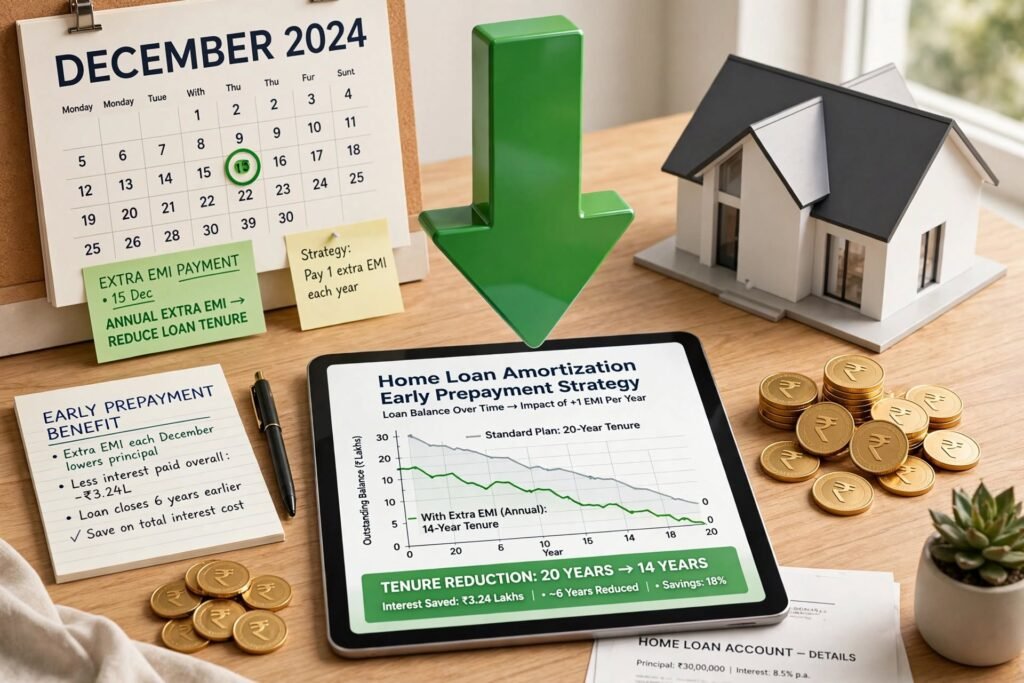
Home loan amortization schedules are front-loaded, meaning a major portion of your EMIs during the first 5 to 10 years goes toward interest rather than principal repayment. Therefore, early prepayments yield the highest interest savings.
Effective Prepayment Strategies:
- The 1 Extra EMI Rule: Pay just one additional EMI every year toward your principal. Doing this on a 20-year home loan can reduce your tenure by nearly 3 to 4 years.
- Increase EMI with Salary Hikes: Step up your EMI amount by 5% to 10% every year as your income increases. Over time, this accelerates principal reduction significantly.
- Utilize Annual Windfalls: Allocate annual performance bonuses, tax refunds, or lump sum investment gains directly toward partial prepayments.
3. Reduce Tenure Instead of Lowering EMI
When interest rates drop or when you make a partial lump sum prepayment, banks often offer you two options:
- Reduce your monthly EMI amount (keeps the tenure the same).
- Reduce your loan tenure (keeps the monthly EMI amount the same).
Pro Tip: Always opt to reduce loan tenure. Keeping your EMI constant while shortening the tenure maximizes interest savings and frees you from debt faster.
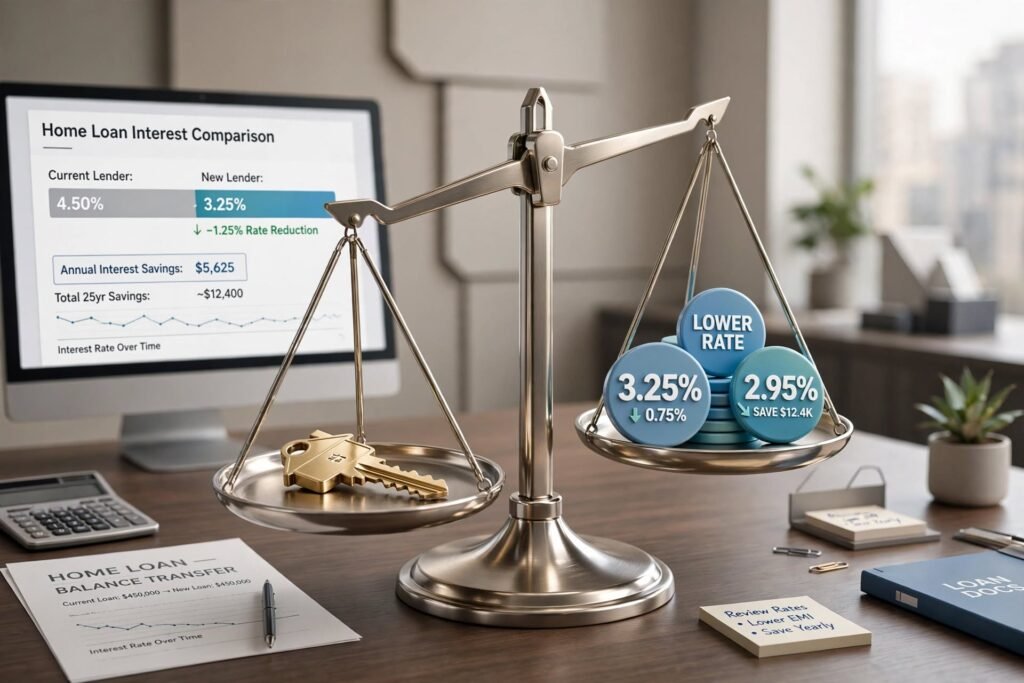
4. Explore Home Loan Balance Transfer (HLBT)
If your existing bank refuses to lower your interest rate despite market rate cuts, consider transferring your remaining loan balance to another financial institution offering a lower rate.
Before Transferring, Check:
- Processing fees and legal costs: Calculate whether the interest savings outweigh the transfer fees charged by the new lender.
- Remaining tenure: A balance transfer is most beneficial during the first half of your loan tenure when interest charges dominate your EMIs.
5. Maximize Tax Benefits Under the Income Tax Act
A home loan provides several tax deductions that lower your overall tax outgo. Understanding how to claim them effectively helps increase your net savings:
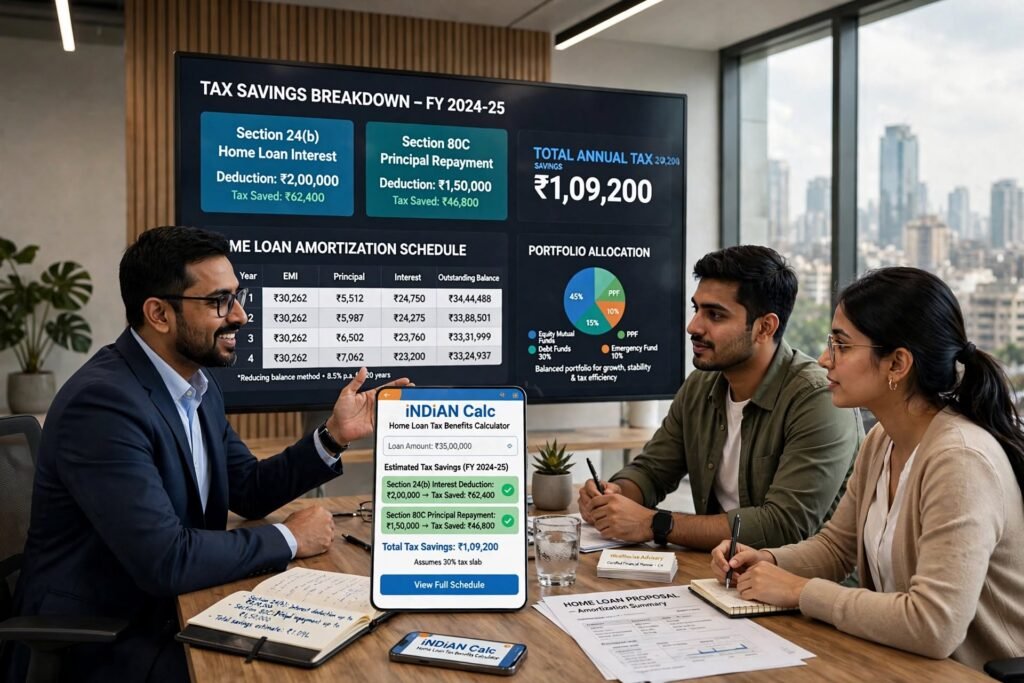
- Section 24(b): Deduct up to ₹2,00,000 per financial year on interest paid for self-occupied properties.
- Section 80C: Deduct up to ₹1,50,000 per financial year on principal repayments (available under the Old Tax Regime).
- Joint Home Loans: If you co-own the property and co-sign the loan with a spouse or family member, both borrowers can claim individual tax deductions, doubling the total benefits.
6. Maintain an Emergency Fund and Insurance Protection
A long-term loan requires a safety net to ensure you never default during unexpected life events such as job loss or medical emergencies.
- Maintain a 6-month EMI reserve: Keep 3 to 6 months’ worth of EMIs liquid in a high-yield savings account or liquid mutual fund.
- Get Home Loan Term Insurance: Purchase a pure term insurance policy or home loan protection plan covering the outstanding loan balance to protect your family from financial distress in your absence.
Calculate Your Home Loan EMIs & Prepayment Savings
Before committing to a repayment schedule or making partial prepayments, use our smart digital calculators to visualize your savings instantly:
- Calculate exact monthly outgoes and total interest breakdowns with our free Home Loan EMI Calculator.
- Deciding whether to prepay your loan or invest extra funds in equity? Use our SIP and Mutual Fund Calculator to compare potential returns.
- Check official interest rate policies and regulatory guidelines directly at the Reserve Bank of India (RBI) portal.
Frequently Asked Questions (FAQs)
1. Should I prepay my home loan or invest in mutual funds (SIP)?
If your home loan interest rate is 8.5% and expected mutual fund returns are 12%, investing via SIP may offer higher net growth mathematically. However, prepaying your loan provides a guaranteed risk-free return equal to your interest rate and brings psychological peace of mind.
2. Is there any penalty for prepaying a floating-rate home loan?
According to RBI guidelines, banks and NBFCs in India cannot charge prepayment penalties or foreclosure fees on individual floating-rate home loans.
3. How often should I review my home loan terms?
It is advisable to review your home loan interest rate, outstanding balance, and amortization schedule once every year or whenever central bank interest rate policies change.
Disclaimer: The information provided in this article is strictly for educational and informational purposes only. It should not be construed as direct financial, banking, or legal advice. Home loan terms, interest rates, and tax laws are subject to change; always consult a qualified financial advisor or bank officer before making major financial decisions.