Building long-term wealth through mutual funds is one of the smartest financial decisions you can make. However, the moment you decide to invest your hard-earned money, a fundamental question arises: Should you invest via a Systematic Investment Plan (SIP) or make a one-time Lump Sum investment?
Both strategies have unique advantages depending on market conditions, your income stream, and personal risk tolerance. In this comprehensive guide, we will break down the core differences between SIP vs Lump Sum investment strategy, analyze real-world scenarios, and help you determine which method aligns best with your financial goals in 2026.
What is a Systematic Investment Plan (SIP)?
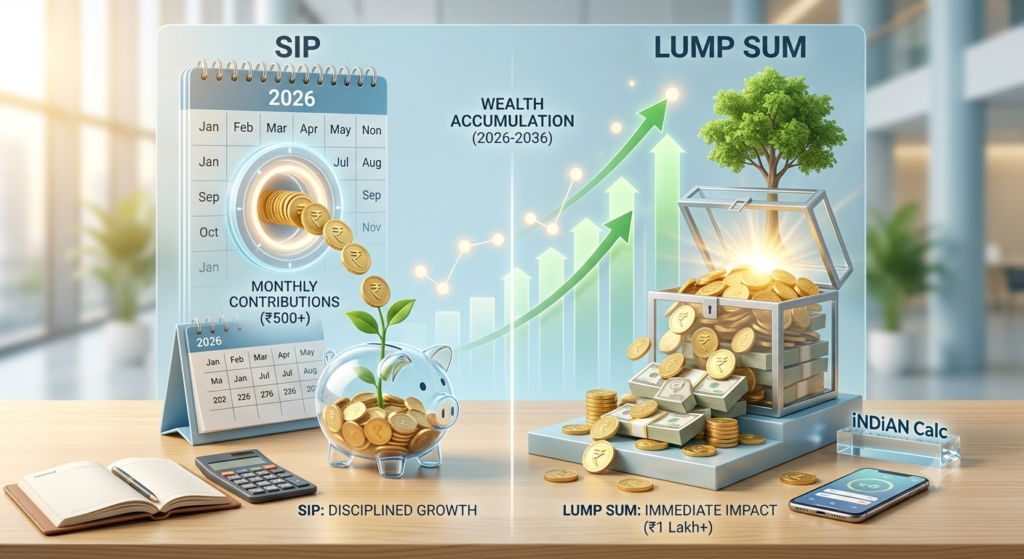
A Systematic Investment Plan (SIP) allows you to invest a fixed amount of money at regular intervals—weekly, monthly, or quarterly—into a chosen mutual fund scheme.
Key Benefits of SIP:
- Rupee Cost Averaging: When market prices (NAV) fall, your fixed monthly installment buys more mutual fund units. When markets rise, you buy fewer units. Over time, this lowers your average purchase cost without requiring you to time the market.
- Disciplined Financial Habit: SIPs automate your savings habit. The fixed amount gets deducted automatically from your bank account every month.
- Low Entry Barrier: You can start your wealth-building journey with as little as ₹500 per month.
What is a Lump Sum Investment?
A Lump Sum investment involves depositing a substantial amount of money into a mutual fund scheme in a single transaction.
Key Benefits of Lump Sum:
- Maximum Compounding Power: Since the full amount is invested upfront, every rupee gets exposed to compounding returns right from day one.
- Ideal for Market Corrections: If the stock market experiences a sharp downturn or correction, buying a lump sum at lower valuations can generate exceptional returns during the recovery phase.
- Suitable for Windfalls: It is the most effective way to deploy one-time cash inflows like annual performance bonuses, property sales proceeds, or inheritance money.
SIP vs Lump Sum: A Side-by-Side Comparison
To quickly understand how these two strategies stack up against each other, review the comparative breakdown below:
| Investment Factor | Systematic Investment Plan (SIP) | Lump Sum Investment |
| Capital Requirement | Small regular amounts (e.g., ₹1,000/month) | Single large upfront payment |
| Market Timing Risk | Very Low (Averages market volatility) | High (Requires favorable market entries) |
| Volatiliy Protection | Excellent due to Rupee Cost Averaging | Low during market peaks |
| Best Suited For | Salaried employees with regular monthly income | Investors with lump sum windfalls or bonuses |
| Compounding Duration | Incremental compounding on monthly deposits | Immediate full compounding on total capital |
Which Investment Strategy Yields Better Returns?
To evaluate performance, let us consider a practical scenario under varying stock market conditions:
Scenario A: In a Rising (Bull) Market
When stock markets consistently trend upward, Lump Sum investments generally outperform SIPs. This happens because your entire capital earns returns from the lowest entry price, whereas SIP installments buy units at progressively higher NAV prices each month.
Scenario B: In a Volatile or Declining (Bear) Market
In fluctuating or declining markets, SIP is overwhelmingly superior. As market indices fall, your SIP acquires more units at discounted rates. When the market eventually rebounds, the accumulated low-cost units deliver significantly higher compound returns compared to a lump sum locked in at peak levels.
Strategic Checklist: How to Choose in 2026
Follow this practical decision-making framework before committing your capital:
- Assess Your Cash Flow: If you receive a monthly paycheck, setting up an automated SIP ensures disciplined long-term saving without straining your monthly liquidity.
- Evaluate Market Valuations: If market indices are trading near all-time high valuations, avoid putting your entire savings into a lump sum. Instead, consider spreading your capital over 12–18 months using a Systematic Transfer Plan (STP) or a monthly SIP.
- Combine Both Strategies: You do not have to choose just one. A proven approach used by smart investors is running regular monthly SIPs while adding occasional Lump Sum top-ups during temporary market corrections.
Plan Your Wealth Building Strategy Instantly
Calculating future returns manually can be complex due to compounding variables. Use our clean, lightning-fast digital utility tools to simulate your wealth growth in seconds:
- Test different monthly contributions and inflation projections using our free SIP and Investment Calculator tool.
- Evaluating home financing options alongside your mutual fund investments? Calculate your exact monthly outgo with our Home Loan EMI Calculator.
- Review regulatory mutual fund guidelines directly at the Securities and Exchange Board of India (SEBI) portal.
Frequently Asked Questions (FAQs)
1. Can I switch from a Lump Sum to a SIP later?
Yes, you can park your lump sum amount in a liquid fund and use a Systematic Transfer Plan (STP) to automatically transfer a fixed amount into an equity fund every month.
2. Is SIP completely risk-free?
No investment in equity mutual funds is entirely risk-free. However, SIPs significantly reduce market timing risk by averaging out short-term market volatility over a long period.
3. What is the minimum amount required for a Lump Sum investment?
Most mutual fund houses in India allow lump sum investments starting from ₹1,000 to ₹5,000, depending on the scheme’s terms.
Disclaimer: The information provided in this article is strictly for educational and informational purposes only. It should not be construed as direct financial, investment, or legal advice. Mutual fund investments are subject to market risks; always read all scheme-related documents carefully and consult a qualified financial advisor before making any investment decisions.