Meta Description: What is a credit score (CIBIL score) and why is it crucial for loan approvals? Learn how credit scores work and actionable tips to boost your score naturally.
Introduction: The Hidden Digital Report Card of Your Financial Life
When you apply for a home loan, car loan, or even a credit card, banks don’t just look at your current income—they evaluate your financial trustworthiness using a single three-digit number known as your Credit Score (commonly referred to in India as your CIBIL Score).
This score acts as your digital financial reputation. A high score opens doors to lower interest rates, faster loan approvals, and premium financial products, while a low score can lead to repeated loan rejections. In this comprehensive guide, we will break down what a credit score is, how it is calculated, and what steps you can take to keep it in the healthy zone.
What is a Credit Score and How Does It Work?
A credit score is a numerical summary (typically ranging from 300 to 900) of your credit history, compiled by credit bureaus based on how you have managed past loans and credit cards.
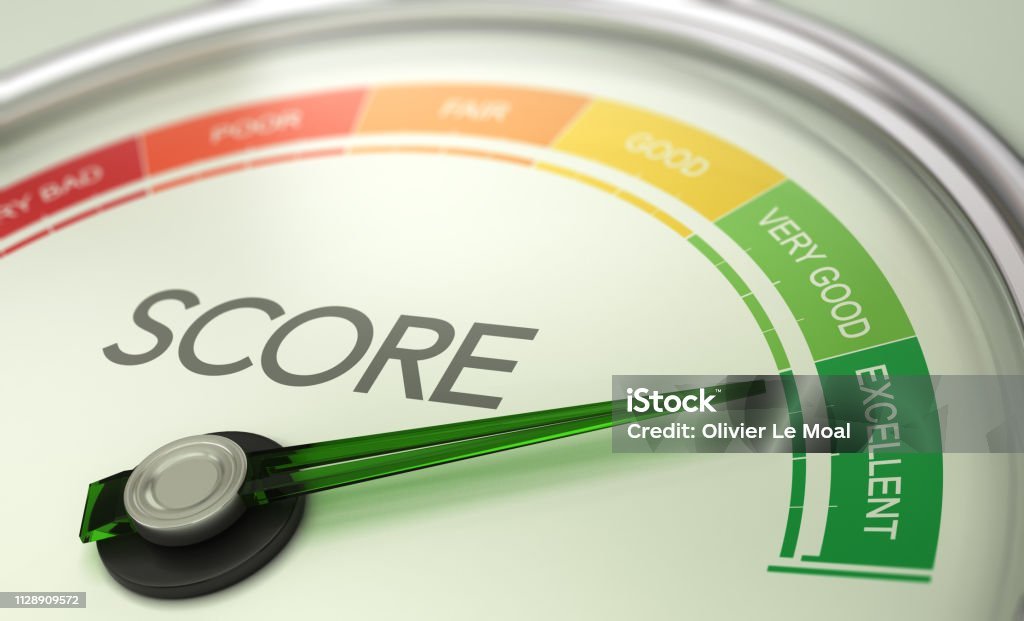
- 750 and Above: Considered an excellent score. Lenders view you as a low-risk borrower, offering you the best interest rates and instant approvals.
- 700 to 749: Good score. Most loan applications are approved smoothly with competitive terms.
- Below 650: Fair to poor score. Lenders may consider you high-risk, leading to loan rejections, higher interest charges, or demands for collateral.
Key Factors That Impact Your Credit Score
Your score is not random; it is calculated using several core parameters tracked by credit bureaus:
- Repayment History (35%): This is the single most important factor. Making your loan EMIs and credit card bill payments on time every single month builds a stellar record. Even a single delayed payment can cause a sharp drop.
- Credit Utilization Ratio (30%): This measures how much of your available credit limit you are using. If your total credit card limit is $10,000 and you regularly spend $8,000, your utilization is high (80%), signaling financial stress. Keeping utilization under 30% is ideal.
- Credit History Length (15%): Older credit accounts show long-term stability. Keeping your oldest credit card active (even with zero balance) helps boost your average account age.
- Credit Mix and New Inquiries (20%): Having a healthy mix of secured loans (like home loans) and unsecured loans (like credit cards) is good. However, applying for multiple new loans or credit cards in a short span creates “hard inquiries,” which negatively impact your score.
5 Practical Tips to Improve and Maintain a High Credit Score
- Never Miss a Due Date: Set up auto-debit instructions or payment reminders for all your utility bills, loan EMIs, and credit card dues to ensure 100% on-time payments.
- Keep Your Credit Utilization Low: Pay off your credit card balances multiple times a month if necessary to ensure your statement closing balance remains well below 30% of your total limit.
- Check Your Credit Report Regularly: Mistakes happen. Review your official credit report at least once a year to spot any reporting errors, clerical mistakes, or fraudulent accounts, and raise a dispute immediately if found.
- Avoid Multiple Hard Inquiries: Don’t apply for loans or credit cards everywhere at once. Each rejection or simultaneous application lowers your score further. Compare options online first.
- Maintain Older Accounts: Resist the temptation to close your oldest credit cards, as a longer credit history directly strengthens your credit profile.
Frequently Asked Questions (FAQs)
Q1: Does checking my own credit score lower it?
Ans: No. Checking your own score counts as a “soft inquiry,” which has zero impact on your credit score. Only inquiries made by lenders when you apply for a loan (“hard inquiries”) affect it.
Q2: How long does it take to repair a damaged credit score?
Ans: Rebuilding a credit score takes time and consistent discipline. Depending on how severe the damage was, maintaining on-time payments and low credit utilization typically takes 6 to 12 months to show noticeable improvement.
Conclusion
Your credit score is a vital asset in your modern financial toolkit. By practicing disciplined repayment habits, managing your credit utilization wisely, and keeping a close eye on your financial reports, you can secure financial freedom and access the best market rates whenever you need capital.
Disclaimer: This article is for informational and educational purposes only. Credit score policies and bureau algorithms vary by region; consult certified financial advisors for personalized debt management guidance.